
Introduction
Getting an Allstate homeowners insurance quote can help you estimate what you may pay to protect your house, belongings, and personal liability. However, the quoted premium is not based on the home’s purchase price alone. Factors such as location, property characteristics, coverage limits, deductible, insurance history, and available discounts can all affect the cost.
For homeowners comparing policies, the most useful approach is to look beyond the headline price. Understanding what an Allstate home insurance quote includes, which factors influence it, and what coverage options are available can make it easier to compare policies on an equal basis.
Quick Answer: What Is an Allstate Homeowners Insurance Quote?
An Allstate homeowners insurance quote is an estimate of the premium you may pay for a home insurance policy based on information about you, your property, the coverage you select, and other rating factors.
Allstate says homeowners requesting a quote may need to provide information such as the property’s address, home condition, renovations, amenities, and requested coverage limits. Your deductible and selected coverages can also affect the price.
The actual premium can vary considerably between homeowners because no two properties have exactly the same risks or insurance requirements.
Key Facts at a Glance
| Factor | Why It Matters |
|---|---|
| Home location | Local risks and claims can affect pricing |
| Home age | Older properties may present different repair risks |
| Home size | Larger homes can require more coverage |
| Construction | Materials and building characteristics can affect costs |
| Roof and major systems | Condition can influence risk and insurability |
| Coverage limits | Higher limits generally mean more protection and can affect premiums |
| Deductible | A higher deductible may reduce the premium but increases your out-of-pocket cost after a covered claim |
| Claims history | Previous claims may influence pricing |
| Personal property | The value and type of belongings influence coverage needs |
| Discounts | Bundling, security features, payment history and other factors may create savings opportunities |
What Is Allstate Homeowners Insurance?
Allstate homeowners insurance is designed to help protect eligible residential properties and the people who own them against covered losses.
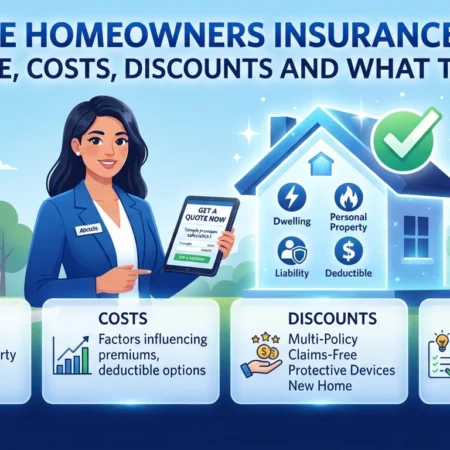
A typical homeowners policy can include several different types of protection. Allstate identifies dwelling coverage, personal property coverage, liability protection, other structures coverage, guest medical protection, and additional living expenses among the types of coverage that may be available depending on the policy and location.
The exact coverage available can vary by state and policy. That distinction matters because homeowners insurance is not identical everywhere.
For example, a homeowner in an area with significant storm exposure may have different insurance considerations from someone living in a region with different property risks.
Dwelling Coverage
Dwelling coverage generally applies to the physical structure of the insured home, including components such as walls and the roof, subject to the policy’s terms, exclusions, limits, and deductible.
The appropriate dwelling limit should reflect the estimated cost to repair or rebuild the structure rather than simply the property’s market value.
Personal Property Coverage
Personal property coverage can help protect belongings such as furniture and electronics after covered losses.
Allstate explains that personal property coverage can be based on either actual cash value or replacement cost coverage, depending on the policy. Actual cash value accounts for depreciation, while replacement cost coverage can help pay for a new item of similar kind and quality, subject to policy terms and limits.
High-value possessions may require additional consideration. Scheduled personal property coverage can be available for certain valuable items, such as jewelry.
Liability Protection
Homeowners insurance can also provide personal liability protection.
This coverage may help when the policyholder is legally responsible for another person’s injury or property damage, subject to the policy’s terms and limits. Allstate notes that liability coverage can involve expenses such as medical costs and legal defense in qualifying situations.
Additional Living Expenses
If a covered loss makes a home uninhabitable, additional living expense coverage may help pay certain increased costs associated with temporary living arrangements.
Depending on the policy, examples can include hotel or temporary rental expenses and certain additional food or pet-boarding costs. Coverage has limits and applies only to qualifying circumstances.
How an Allstate Homeowners Insurance Quote Works
The quoting process starts with information about the homeowner and property.
Allstate says homeowners insurance quote information can include the property’s address, personal details, renovations, repairs, home condition, amenities, and requested coverage. The insurer may also obtain some property information through available records such as local building permits.
The quote is then influenced by the coverage structure selected.
For example, changing the dwelling limit or deductible can affect the premium. Adding additional coverage for valuable possessions can also change the overall cost.
This means two homes in the same neighborhood can receive different quotes.
A Quote Is Not the Same as a Final Policy
A quote should be viewed as an estimate based on the information provided.
The final policy documents establish the actual coverage, limits, deductibles, exclusions, and premium. Allstate’s declarations page, for example, lists important details such as the total premium, policy period, coverage limits, discounts, and deductibles.
Before purchasing coverage, review those details carefully rather than relying only on the initial quote amount.
What Information Do You Need for an Allstate Home Insurance Quote?
Having the relevant information ready can make the quoting process easier and improve the consistency of comparisons.
1. Property Address
The home’s location is one of the fundamental pieces of information used during the quoting process.
Location can influence pricing because insurers consider factors associated with the property’s area, including local claims experience and geographic risks.
2. Home Age and Size
The age and size of the home can affect insurance considerations.
Square footage, construction materials, and the building’s age are among the property characteristics that may influence premiums.
3. Roof Information
The roof is particularly important because it is a major part of the home’s structure and can be exposed to weather-related damage.
Information about roof age, condition, and construction may therefore be relevant when obtaining coverage.
4. Renovations and Major Systems
Recent improvements can matter when requesting a quote.
Allstate specifically notes that insurers may ask about renovations, repairs, plumbing, water heaters, fireplaces, bathrooms, and other features that help describe the home’s condition.
5. Personal Belongings
Consider the approximate value of your furniture, electronics, clothing, appliances, and other possessions.
A basic inventory can help you think about whether the personal property limit is appropriate.
6. Current Insurance Information
Your existing coverage and insurance history can be relevant when comparing policies.
Claims history and periods of continuous coverage can affect premium calculations and, in some circumstances, the coverage options available.
What Determines the Cost of an Allstate Homeowners Insurance Quote?
There is no universal Allstate homeowners insurance price that applies to every homeowner.
The company states that factors affecting home insurance costs can include the home’s value and belongings, deductible, claims history, age, and location.
Other property characteristics can also influence the quote.
Location
Where the home is located can have a major impact.
Insurers may consider local claim patterns, proximity to certain hazards, fire protection resources, and other geographic characteristics.
Home Construction
Construction materials and the home’s physical characteristics help determine potential repair or rebuilding costs.
Square footage, building materials, and age are among the factors that may influence premiums.
Deductible
The deductible represents the amount you pay toward a covered loss before insurance benefits apply.
Generally, choosing a higher deductible can reduce the premium, but it also means taking on more out-of-pocket expense when a covered claim occurs.
Claims History
A history of previous claims can affect pricing.
Allstate identifies insurance history, including claim frequency and continuous coverage, as factors that may influence premiums.
Coverage Limits
More protection can affect the premium.
For instance, a homeowner with a larger property and substantially more personal property may need higher limits than someone with a smaller home and fewer belongings.
The important point is to choose limits based on actual protection needs rather than simply trying to obtain the lowest quote.
How Deductibles Affect Your Allstate Quote
A deductible creates an important trade-off.
Suppose two policies provide broadly similar protection but have different deductibles. The policy with the higher deductible may have a lower premium, while the homeowner would be responsible for a larger portion of a covered loss before insurance pays.
Consider your emergency savings when choosing a deductible.
A deductible that looks attractive because it reduces the premium may become difficult to manage after a major covered event.
Allstate recommends comparing policies using the same deductibles and coverage limits so that price comparisons are more meaningful.
Allstate Homeowners Insurance Discounts
Discounts can make a difference in the final premium, although availability and eligibility can vary.
Allstate currently lists several homeowners insurance savings opportunities.
Multi-Policy Discount
Bundling home and auto policies with Allstate may provide a multi-policy discount in eligible situations.
Responsible Payer Discount
Allstate lists savings associated with payment history and certain payment arrangements.
Claim-Free Discount
Homeowners who switch to Allstate without a recent home insurance claim may qualify for a claim-free discount, subject to eligibility requirements.
Protective Device Discount
Safety and security equipment may also create discount opportunities.
Examples listed by Allstate include burglar alarms, deadbolts, smoke detectors, fire extinguishers, sprinklers, and certain monitored alarms.
Other Potential Savings
Allstate also lists opportunities such as welcome and loyalty discounts, home buyer discounts, automatic-payment savings, early-signing discounts, and certain windstorm mitigation discounts in Florida. Availability depends on applicable eligibility rules.
The safest approach is to ask which discounts are actually available for your property and location instead of assuming every listed discount applies.
How to Compare an Allstate Quote With Other Insurers
Price comparison works best when the policies are genuinely comparable.
Getting a lower premium from another insurer does not necessarily mean you are receiving the same level of protection.
Compare These Items
When reviewing an Allstate quote against another insurer, put the following side by side:
- Dwelling coverage limit
- Other structures coverage
- Personal property limit
- Liability limit
- Additional living expense coverage
- Deductibles
- Covered perils
- Exclusions
- Optional endorsements
- Personal property valuation method
- Available discounts
- Total premium
Allstate recommends comparing coverage types, limits, deductibles, and endorsements rather than looking only at price.
Using identical or closely comparable limits makes the results much more useful.
Common Mistakes When Comparing Home Insurance Quotes
Choosing the Lowest Number Immediately
A low premium can look appealing, but the policy may have different limits or a higher deductible.
Check the coverage structure first.
Using the Home’s Purchase Price as the Only Measure
The amount paid for a property does not automatically determine the appropriate dwelling coverage.
Rebuilding costs can depend on construction, labor, materials, location, and other characteristics.
Forgetting Personal Property
Homeowners sometimes focus heavily on the building while overlooking everything inside it.
Create a household inventory so you have a clearer picture of the amount of personal property coverage you may need.
Ignoring Valuable Items
Jewelry, collectibles, expensive electronics, artwork, and other high-value belongings may have special limits under a standard policy.
Ask whether specific items need additional coverage.
Increasing the Deductible Without Planning
A higher deductible can lower the premium, but you need to be financially prepared to pay that amount after a qualifying claim.
Is the Cheapest Homeowners Quote Always Better?
Not necessarily.
The purpose of homeowners insurance is to provide financial protection against covered risks, so the policy needs to match the homeowner’s circumstances.
A useful comparison asks two separate questions:
How much does the policy cost?
and
What protection does that price provide?
A policy with a slightly higher premium may have different coverage limits, deductibles, or optional protections. Another policy may be less expensive but require a larger out-of-pocket contribution after a covered loss.
Allstate itself recommends comparing coverage, limits, deductibles, endorsements, and other policy details alongside price.
How to Prepare Before Requesting an Allstate Quote
A little preparation can make the process more efficient.
Make a Home Inventory
Record major belongings and, where practical, keep receipts, photographs, serial numbers, or other documentation.
Check Your Roof and Major Systems
Know approximately when the roof, plumbing, electrical system, HVAC equipment, and water heater were installed or updated.
Review Previous Insurance Information
Have your current policy details and claims history available.
Think About Your Deductible
Decide what amount you could reasonably pay from savings after a covered loss.
Identify Valuable Possessions
Make a separate list of jewelry, collectibles, high-end electronics, artwork, or other items that may need special consideration.
Ask About Discounts
Do not assume a discount automatically applies.
Ask specifically about bundling, security devices, payment options, claim-free status, home improvements, and other available savings opportunities.
Frequently Asked Questions
How much is an Allstate homeowners insurance quote?
There is no single price for every homeowner. The premium depends on factors such as location, home characteristics, coverage limits, deductible, claims history, personal property, and other rating factors.
What information does Allstate need for a homeowners quote?
You may need to provide the home’s address, personal information, property details, renovations, condition, amenities, and the coverage and limits you want.
Does Allstate offer homeowners insurance discounts?
Yes. Allstate lists discounts and savings opportunities that can include multi-policy bundling, claim-free status, responsible payment history, protective devices, home buyer status, automatic payments, and other qualifying circumstances.
Does a higher deductible reduce homeowners insurance costs?
A higher deductible will typically result in a lower premium, but the homeowner assumes more out-of-pocket expense when a covered claim occurs.
Does Allstate homeowners insurance cover personal belongings?
Personal property coverage can help protect eligible belongings such as furniture and electronics after covered losses. The policy may use actual cash value or replacement cost provisions depending on the coverage selected.
Can I bundle Allstate home and auto insurance?
Allstate offers multi-policy discounts for eligible customers who bundle policies, although availability and terms can vary by location and policy.
Does homeowners insurance cover every type of damage?
No. Homeowners policies contain exclusions, conditions, limits, and deductibles. Coverage depends on the specific policy and applicable state rules. Review the policy documents carefully before assuming a particular loss is covered.
How should I compare an Allstate quote with another company?
Use the same or closely comparable coverage limits and deductibles, then compare premiums, exclusions, endorsements, discounts, and other policy terms. Comparing only the monthly or annual price can produce a misleading result.
Final Thoughts
An Allstate homeowners insurance quote is more than a number attached to your property. It represents an estimate based on the home’s characteristics, your requested protection, deductible, insurance history, location, and other factors.
The most useful way to evaluate a quote is to understand what you are actually purchasing.
Start by reviewing dwelling coverage, personal property protection, liability coverage, additional living expenses, deductibles, exclusions, and optional protections. Then check which discounts you may qualify for and compare the result with other insurers using similar coverage limits.
Because insurance rules and available products can vary by state, always review the policy documents and current quote details applicable to your location before purchasing coverage.

No Comment! Be the first one.